
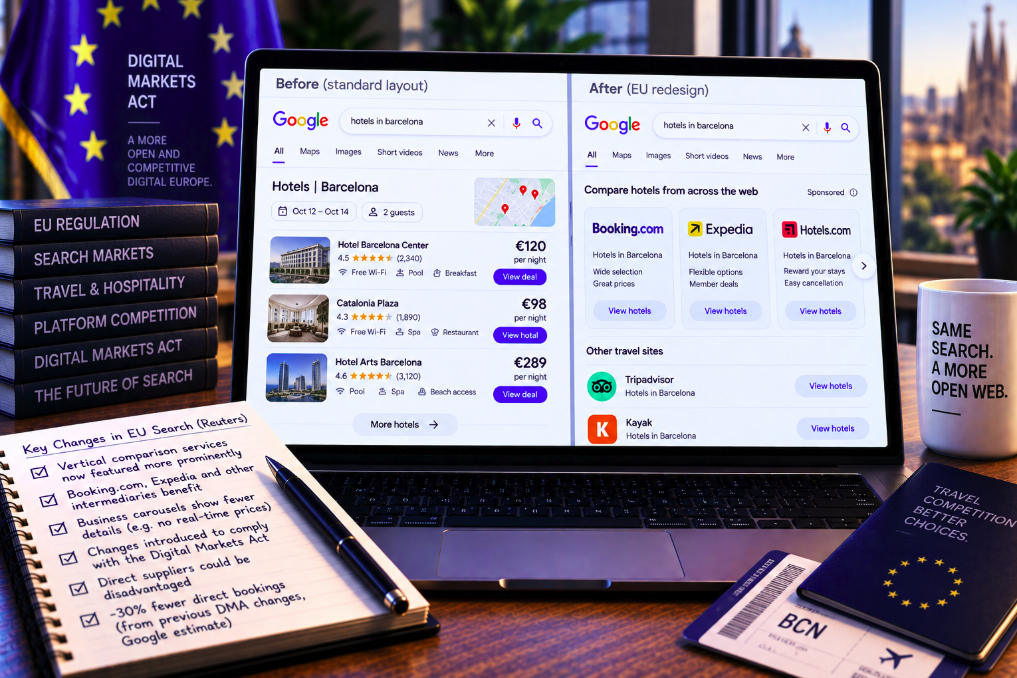
Google is redesigning some of its most commercially important search results in Europe, giving specialist comparison services more prominent placement while stripping features from the direct hotel, flight and restaurant experiences that have long kept users inside Google’s own interface.
The changes, reported by Reuters on September 8, are part of Google’s continuing effort to comply with the European Union’s Digital Markets Act. In searches involving categories such as hotels, flights and restaurants, the revised format can place one vertical search service prominently in the results followed by two additional specialist services.
At the same time, some business carousels are becoming less feature-rich. Reuters reports that information such as real-time pricing is being removed from parts of the direct listing experience, reducing the amount of transactional information users can obtain before clicking elsewhere.
For European travel and local-search businesses, the change is more than a cosmetic SERP redesign. It alters which type of website Google gives the most visible path to the customer: the direct supplier or an intermediary that compares multiple suppliers.
Comparison services move closer to the center of the SERP
The Digital Markets Act was designed in part to prevent designated gatekeepers from using their control of major platforms to unfairly privilege their own services.
Google Search is one of the products caught in that regulatory framework. For years, the company has integrated specialized experiences directly into Search, including hotel listings, flight information, maps, prices and local business details.
Those features can be useful to consumers, but competitors have argued that Google’s ability to place its own specialized search modules above or around conventional organic results makes it harder for independent comparison services to compete.
The new European design shifts more visibility toward vertical search services, or VSSs: specialist platforms that aggregate and compare offers from multiple businesses.
In travel, that means companies such as Booking.com and Expedia can gain a more prominent route into the user journey instead of competing only with direct hotel websites beneath a feature-rich Google module.
The new format highlights one specialist service, then two more
According to Reuters, the revised format places one vertical search service in a prominent position and follows it with two additional services.
That structure matters because placement inside a modern search results page is not equivalent to another blue link in a list. Rich modules can dominate the visible screen, particularly on mobile, and can direct user attention before conventional organic results are reached.
A dedicated comparison-services area therefore gives intermediaries a new kind of distribution opportunity. Even if a hotel’s own website continues to rank organically, the consumer may first encounter an interface explicitly designed to send them through a comparison layer.
For SEO teams, this creates another search surface to monitor. Visibility in European travel and local search may increasingly depend not only on ranking a direct domain but also on how a business is represented within the intermediaries Google chooses to feature.
Direct business carousels lose some of their utility
The other side of the redesign is the reduction of information inside some direct business modules.
Reuters reports that traditional carousels are losing details including real-time prices. That can make the direct supplier path less informative at the exact moment comparison services are becoming more visible.
The combination is strategically significant. A hotel card that once allowed a user to assess price and availability directly from the SERP can become a thinner discovery result, while a nearby comparison service offers a dedicated route for evaluating multiple options.
The same principle can affect restaurants and flights. The more information a user must obtain after leaving the direct Google module, the more valuable the intermediary layer can become.
Google argues that this is a deterioration of the search experience. European regulators and comparison businesses have a different concern: whether a gatekeeper should be able to build a rich proprietary vertical experience that competes with the services it ranks.
Google says the DMA is pushing users toward intermediaries
Google has been publicly criticizing this tradeoff for years.
In a November 2024 DMA compliance update, the company said it had already made more than 20 changes to Search in Europe. Those included dedicated units and formats intended to increase the prominence of comparison sites in categories including flights, hotels and shopping.
Google argued that some of those changes benefited large online travel aggregators while making it harder for hotels, airlines and small retailers to reach customers directly.
The company’s position is that rich Search features can shorten the path between a user and a supplier, while regulations requiring greater intermediary visibility can insert another commercial layer into the transaction.
That is Google’s interpretation of the competitive effect, not an uncontested finding. The DMA exists precisely because European policymakers are skeptical that gatekeepers should be the sole judges of when their integrated services improve competition.
The “30% fewer direct bookings” figure is not a result of this rollout
One statistic surrounding the current change requires particularly careful handling.
Google has previously said that European hotels reported free direct booking clicks falling by as much as 30% following earlier DMA compliance changes. The company repeated that concern in multiple public statements about the impact of the regulation.
That number does not measure the effect of the September 2026 redesign.
It predates the current rollout and comes from Google’s account of what hotels and industry participants reported after previous DMA-related Search changes. It should therefore not be presented as evidence that the new comparison-site layout has already caused a 30% decline in direct hotel bookings.
The distinction is important because the current redesign is too new for a credible before-and-after market effect to be inferred from that older figure.
An earlier hotel test produced a different result
Google has also published data from a separate European experiment that can easily be confused with the 30% claim.
In late 2024, the company temporarily removed certain hotel-search features for users in Germany, Belgium and Estonia. The test replaced rich hotel functionality with a simpler list of links.
In its published results from that experiment, Google said traffic to hotels and intermediary sites fell overall, with hotels losing more than 10% of traffic while intermediary traffic largely stayed flat. Google also reported lower user satisfaction and more difficulty finding hotels.
The company ended the test and restored the previous experience.
That experiment is useful historical evidence that SERP design can materially change traffic distribution, but it is not the same intervention as the September 2026 rollout. The design, markets and treatment differ, so its percentages should not be used as a forecast for the new format.
For hotels, the battle moves from ranking to distribution
Hotels have traditionally approached Google visibility through several parallel channels: organic SEO, Google Business Profile, hotel-price feeds, paid Hotel Ads and visibility within online travel agencies.
The new European layout makes the relationship between those channels even more important.
If comparison services occupy more prominent SERP real estate, a hotel can perform well in organic search while still seeing more users enter the booking journey through an intermediary.
That matters economically because direct bookings and intermediary bookings have different acquisition costs. A direct organic click can lead to a transaction without an OTA commission, while a reservation originating through a large travel marketplace generally carries commercial terms for the supplier.
The SEO question therefore becomes partly a distribution question: not only “Does the hotel appear?” but “Through which commercial path does Google expose the hotel to the customer?”
Restaurants face a similar shift in local discovery
Restaurants are also affected because local search increasingly combines maps, reviews, menus, availability, prices and booking options in a single results experience.
Removing or reducing information from direct business carousels can increase the value of vertical platforms that aggregate restaurants and provide richer comparison or reservation functionality.
For restaurant marketers, this may require broader visibility management. A strong website and complete business profile remain important, but representation on third-party services can become more consequential when Google gives those services dedicated prominence.
That creates an uncomfortable dependency. A restaurant may need to optimize both its own direct presence and the intermediary profiles through which customers increasingly discover it.
Comparison-site SEO becomes more valuable
The redesign may also change the economics of SEO for the comparison platforms themselves.
Historically, a vertical search service could rank as a conventional organic result while competing against Google’s own rich modules. Under the revised European design, being recognized and surfaced as a specialist comparison service can provide a more explicit path into the SERP.
That creates incentives for vertical platforms to expand inventory, structured data, landing-page coverage and relationships with suppliers.
It may also intensify competition among intermediaries. The benefit is not simply “comparison sites win.” If only a limited number of services receive the most prominent placements, the largest and best-established aggregators could capture disproportionate value.
That outcome would satisfy the formal goal of reducing Google’s self-preferencing while potentially concentrating more traffic in another small group of powerful platforms.
Google frames the change as lower quality; the EU frames it as competition
The dispute ultimately rests on two different definitions of a good search result.
Google emphasizes utility. From its perspective, displaying prices, maps, ratings and booking information directly in Search allows users to make decisions faster and reach suppliers more efficiently.
The DMA emphasizes contestability. A search engine that controls the gateway to online demand should not necessarily be allowed to use that position to privilege its own specialized comparison layer over independent services.
Both questions can be real at the same time. A more competitive interface can introduce more clicks or friction. A highly convenient integrated interface can also make it harder for competing services to reach users.
The September redesign is an attempt to resolve that tension through product design, but the commercial consequences will depend on how users actually behave once the new modules become familiar.
The SEO impact cannot be measured from screenshots alone
For European businesses, the next important evidence will come from traffic and conversion data rather than the visual prominence of the new modules.
Hotels should monitor changes in organic sessions, Google Business Profile interactions, direct booking starts, branded queries, OTA referrals and commission-bearing reservations. Restaurants should watch website clicks, calls, direction requests, reservation-platform traffic and the relative share of discovery coming through third parties.
Comparison platforms will want to measure whether increased SERP exposure translates into incremental qualified traffic rather than simply shifting users between Google modules.
Those measurements should also be segmented geographically. The regulatory design applies to European users, making global averages potentially misleading for businesses with substantial traffic outside the region.
Only after enough post-rollout data accumulates will it be possible to distinguish interface visibility from actual commercial impact.
Europe and the rest of Google Search are diverging further
The redesign reinforces a broader trend: Google Search is no longer one globally uniform product.
Regulation increasingly determines which features can appear, how services are linked and which competitors receive dedicated access to valuable search surfaces.
That divergence is especially visible in travel. While European Search is being restructured around DMA constraints, Google continues to add richer travel capabilities elsewhere in its ecosystem, including conversational hotel and flight tools in AI Mode.
For multinational SEO teams, this makes regional SERP monitoring essential. A ranking strategy built around what users see in the United States may not describe the commercial journey available to a user in France, Germany, Italy or Spain.
Direct suppliers should prepare for a more intermediary-heavy search journey
The immediate strategic response should not be to abandon direct SEO. Direct visibility becomes more valuable, not less, when an intermediary path becomes easier for users to take.
Hotels and restaurants should make their own sites fast, authoritative and transaction-ready, maintain accurate structured data and local information, and protect branded search demand. At the same time, they may need to treat major comparison and booking platforms as search-distribution channels rather than merely downstream marketplaces.
The most important metric is likely to be the mix between direct and intermediary acquisition. A business can maintain total Google-driven demand while losing margin if more of those customers arrive through commission-bearing platforms.
That is why the older 30% claim should not be used as the headline measurement of this rollout. The real question is what happens next to the distribution of clicks, bookings and revenue under the new European interface.
The DMA is now changing the architecture of search, not just the rules around it
The latest European redesign shows how deeply regulation can reach into the structure of a search results page.
Google is giving vertical comparison services more explicit prominence in hotel, flight and restaurant searches while reducing some of the rich information available in direct business modules. Google says the result will favor intermediaries such as Booking.com and Expedia and make Search less useful; the regulatory rationale is that independent vertical services need a fairer opportunity to compete with Google’s integrated products.
For SEO, neither narrative is sufficient on its own. What matters is how the new architecture redistributes visibility and transactions.
The up-to-30% decline in free direct booking clicks cited by Google belongs to earlier DMA changes, not the September 2026 rollout. The current redesign still needs its own evidence.
Until that arrives, the clearest conclusion is structural: in European commercial search, ranking a hotel or restaurant directly is becoming only one part of the visibility equation. Increasingly, businesses also have to understand which intermediaries Google places between them and the customer.